By Jonathan Price October 3, 2026
Commercial finance broker registration requirements by state vary significantly in 2026. Virginia and Connecticut expressly require registration of covered commercial-financing brokers. Utah registers covered “providers,” not brokers merely because they broker deals. Georgia, New York’s CFDL, and California’s SB 1235 primarily impose disclosure or conduct requirements rather than a general broker-registration mandate.
Legal and regulatory information verified through October 2, 2026.
That distinction matters for any MCA broker, ISO, sales-based financing broker, or revenue-based financing broker placing deals across state lines. A state can require the broker to register, require the provider to register, require only transaction-level disclosures, or impose more than one of those obligations at the same time.
California also changed its future regulatory framework two days before this verification date. Governor Gavin Newsom signed AB 2116 on September 30, 2026. The law will expand California Financing Law regulation of commercial financing beginning in 2028, including a licensing requirement scheduled for July 1, 2028. It does not convert SB 1235 into a general broker-licensing statute for transactions placed in 2026.
Commercial Finance Broker Registration Requirements by State: 2026 Snapshot
The following table summarizes the commercial finance broker registration requirements by state under the principal commercial-financing statutes discussed in this guide. “No” does not necessarily mean that no other state law can apply; it means the commercial-financing disclosure statute itself does not impose the stated general registration requirement.
| State | Broker Registration / License? | Provider Registration / License? | Main Regulator | Covered Transaction Limit | Key Exemptions | Who Delivers Disclosure? | Renewal / Filing Cycle |
| Virginia | Yes, for covered, nonexempt sales-based financing brokers | Yes | Virginia SCC | Single transaction over $500,000 exempt | Financial institutions; specified five-or-fewer rule | Provider | Direct SCC registration; $500 annual fee due Sept. 15 |
| Utah | No separate broker registration solely for being a broker; conditional if activities make the entity a provider | Yes | Utah DFI | Transaction over $1 million exempt | Depositories, Farm Credit, certain money transmitters, de minimis, real estate, leases, purchase-money and others | Provider | NMLS; expires Dec. 31 |
| Georgia | No registration under §10-1-393.18 | No registration created by that section | Georgia Attorney General | Transaction over $500,000 exempt | Depositories, real estate, leases, purchase-money, de minimis, certain dealer/seller financing | Provider | Not applicable under this statute |
| Connecticut | Yes | Yes | Connecticut Department of Banking | Sales-based financing not exceeding $250,000 under current law | Financial institutions, Farm Credit, real estate, leases, purchase-money, de minimis and others | Provider | NMLS; generally expires Dec. 31; renewal Nov. 1–Dec. 31 |
| New York | No separate CFDL license | No CFDL registration | NYDFS | Transaction over $2.5 million exempt | Financial institutions, Farm Credit, real estate, leases, de minimis, qualifying dealer financing | Provider; broker must transmit disclosures when used | Not applicable under CFDL |
| California | No general SB 1235 broker registration in 2026; separate CFL licensing may apply | SB 1235 itself does not create general provider registration | DFPI | Specific offers up to $500,000 | Depositories, Farm Credit, real-estate-secured and other statutory exemptions | Provider/financer; broker has transmission duties | Not applicable under SB 1235; broader licensing begins in 2028 |
Virginia’s current statute expressly registers providers and brokers. Connecticut’s Department of Banking likewise states that Connecticut has two registration types—provider and broker. Utah’s statute, by contrast, makes it unlawful to conduct covered transactions as a provider without registration.
Registration and Disclosure Are Not the Same Requirement
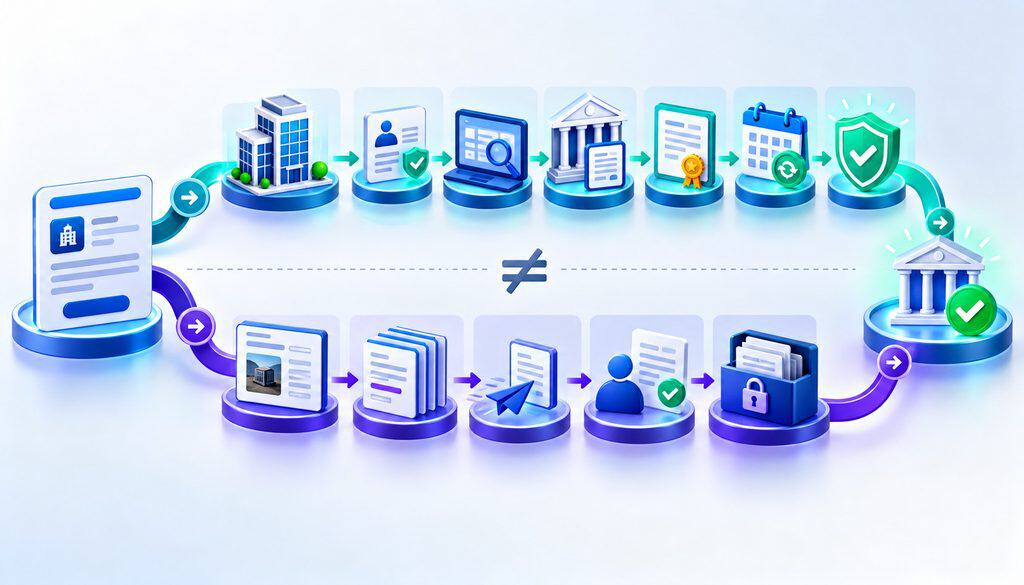
A disclosure statute is not automatically an occupational licensing law. That is the central rule for correctly understanding commercial finance broker registration requirements by state.
Four questions should be answered separately:
- Does the brokerage itself have to register or obtain a license?
- Does the provider or funder have to register or obtain a license?
- Who is legally responsible for generating or delivering the transaction disclosure?
- Can the broker independently create liability by misrepresenting the offer, altering disclosures, or communicating unauthorized terms?
Virginia illustrates why the questions cannot be merged. Virginia requires both a covered sales-based financing broker and provider to register, but §6.2-2231 puts the formal transaction disclosure obligation on the provider.
New York reaches a different result. The CFDL does not create a standalone MCA broker license, but 23 NYCRR §600.21 directly tells an intermediary broker what to do with a specific offer: transmit the financer-provided disclosure unaltered before communicating the offer and give the financer evidence of transmission.
Registration answers who must be authorized to conduct the activity; disclosure rules answer what information must accompany a particular financing offer.
Brokers building a multistate process should therefore review commercial financing disclosure requirements separately from broker registration, especially when handling California or New York offers where an intermediary may have direct transmission or communication duties.
For the controlling legal rules, Virginia’s Sales-Based Financing Act expressly separates broker registration from the provider’s disclosure obligation, while New York’s 23 NYCRR Part 600 sets out the broker’s duty to transmit financer-provided disclosures without alteration.
Virginia Sales-Based Financing Broker Registration
Yes. Virginia requires registration of a covered sales-based financing broker.
The Virginia sales-based financing broker registration requirement appears in Virginia Code Chapter 22.1. A “sales-based financing broker” is a person that, for compensation or an expectation of compensation, obtains or offers to obtain sales-based financing from a provider for a recipient.
Virginia defines sales-based financing as repayment over time as a percentage of sales or revenue. It expressly includes a fixed-payment arrangement when a reconciliation process adjusts the payment to an amount representing a percentage of sales or revenue.
That definition captures many structures commonly described in the market as MCAs or revenue-based financing, provided the statutory elements are met.
Who Must Register?
Virginia Code §6.2-2230 requires every nonexempt sales-based financing provider and sales-based financing broker to register with the State Corporation Commission.
The internet does not provide an avoidance route. Virginia §6.2-2235 expressly applies the chapter when providers or brokers offer, obtain, or make sales-based financing online to or for a Virginia recipient even if they have no physical Virginia location.
The recipient is tied to its principal place of business in Virginia. A provider or broker may rely on a written representation concerning that location or the business address supplied in the financing application.
Registration Mechanics and Fees
Virginia uses the State Corporation Commission, rather than an NMLS commercial-financing filing, for this registration. The implementing regulation requires a completed application, the statutory fee and information requested by the commissioner. A foreign entity must also obtain authority to transact business in Virginia when Virginia corporate law requires it.
The current statutory fees are:
- $1,000 initial registration fee
- $500 annual registration fee
- annual fee due September 15
- failure to pay by September 15 causes the registration to expire automatically by operation of law.
Those amounts appear directly in Virginia Code §6.2-2230.
Virginia Exemptions
Chapter 22.1 does not apply to:
- a financial institution;
- a person, provider, or broker entering into no more than five sales-based financing transactions with a recipient during a 12-month period; or
- a single sales-based financing transaction over $500,000.
The wording of the five-transaction exemption matters. It should not be casually rewritten as a generic “five transactions statewide” exemption.
Who Gives the Disclosure?
The provider must give Virginia’s statutory Sales-Based Financing Disclosure Form when extending a specific offer. Virginia also requires the disclosure to state whether the provider will directly compensate a broker and the amount of that compensation.
That makes the Virginia rule easy to summarize: Virginia sales-based financing broker registration is a broker obligation; transaction disclosure is principally a provider obligation.
Enforcement
Virginia does not say that every deal handled by an unregistered broker automatically disappears. Section 6.2-2236 states more precisely that a provision of a sales-based financing agreement that violates the chapter is unenforceable against the recipient.
The Attorney General may seek an injunction and, where authorized, damages, restitution and other relief.
Virginia’s Sales-Based Financing Act expressly requires covered providers and brokers to register, while the implementing regulations in 10VAC5-240 address the registration application and related filing requirements.
Those primary sources should be checked whenever a brokerage changes entities, control persons, Virginia activity, or its basis for claiming an exemption.
Utah Commercial Financing Registration Requirements
Utah does not require a person to register merely because the person falls within Chapter 27’s definition of “broker.” Registration is triggered by acting as a covered “provider.”
This is the most important correction to a common description of commercial finance broker registration requirements by state. Utah’s statute defines a broker, but §7-27-201 states that beginning January 1, 2023, it is unlawful to engage in a commercial financing transaction as a provider in Utah or with a Utah resident unless registered.
A “broker” generally means a compensated person that obtains a binding commercial-financing offer from a third party and communicates it to a Utah business. But broker status does not, standing alone, create the §7-27-201 registration duty.
Therefore, Utah commercial financing registration DFI analysis should focus first on whether the company’s actual activity makes it a statutory provider.
Covered Products and Exemptions
Utah’s Commercial Financing Registration and Disclosure Act covers business-purpose commercial loans, commercial open-end credit plans and accounts-receivable purchase transactions.
Among the statutory exclusions are:
- depository institutions and specified regulated affiliates;
- Farm Credit providers;
- providers licensed as qualifying money transmitters;
- providers consummating five or fewer commercial financing products in the state during a 12-month period;
- real-property-secured financing;
- UCC leases;
- purchase-money obligations;
- specified motor-vehicle dealer and rental-company transactions;
- qualifying seller-connected financing; and
- commercial financing transactions exceeding $1 million.
Utah DFI and NMLS Filing
The Utah commercial financing registration DFI process runs through NMLS. Utah Code §7-27-201 requires registration information including the entity’s name, principal office, Utah office information where applicable, a Utah designated agent for service, specified criminal-history information and evidence satisfactory to DFI that the entity is registered with NMLS.
Utah DFI’s February 2026 guidance states that applicants complete registration through NMLS using company information and document uploads.
The state fees currently listed by DFI are:
- $300 initial registration fee
- $200 subsequent annual renewal fee.
Registration expires December 31 each year. The current statute requires renewal and the annual fee to maintain authority.
For a Utah filing, first determine whether the entity’s activity makes it a statutory provider under Utah Code Title 7, Chapter 27. If registration is required, the current Utah DFI commercial-financing instructions and DFI’s 2026 registration FAQ provide the filing route, current state fees, and NMLS-related requirements.
Utah Enforcement and Private Actions
Utah may receive complaints, seek voluntary compliance, and commence administrative or judicial proceedings.
A violation carries a statutory civil penalty of $500 per violation, capped at $20,000 for violations arising from the same transaction documentation or materials. After written notice of a previous violation, the figures become $1,000 per violation and an aggregate $50,000 cap for the same documentation or materials.
Utah expressly provides both that Chapter 27 creates no private right of action and that a violation does not affect enforceability of the underlying agreement.
Georgia Commercial Financing Law: What Brokers Actually Have to Do
Georgia’s commercial financing statute regulates disclosures and broker conduct, but it does not create a general commercial financing broker registration program.
Georgia’s SB 90 became effective January 1, 2024 and is codified at O.C.G.A. §10-1-393.18. The official enacted legislation defines a broker, provider, commercial financing transaction and the statute’s exemptions.
For anyone researching Georgia commercial financing disclosure law brokers, that distinction should be stated plainly: Georgia regulates brokers without licensing them under §10-1-393.18.
Covered Transactions
The statute covers business-purpose:
- commercial loans;
- commercial open-end credit plans; and
- accounts-receivable purchase transactions.
Transactions over $500,000 are excluded.
Additional exclusions cover specified federally insured institutions and affiliates, Farm Credit providers, qualifying money transmitters, a provider within the statute’s de minimis limit, real-property-secured transactions, leases, purchase-money obligations, certain motor-vehicle financing, specified seller-connected financing and certain healthcare receivables transactions.
Provider Versus Broker Obligations
The provider gives the required commercial-financing disclosure before consummation.
Brokers are separately prohibited from practices including collecting prohibited advance fees and making false or misleading representations or omitting material facts in connection with their broker services. That is why Georgia commercial financing disclosure law brokers cannot treat the absence of a broker license as an absence of legal duties.
Enforcement
The Attorney General can receive complaints, seek voluntary compliance, and commence administrative or judicial proceedings.
Civil penalties are $500 per violation, subject to a $20,000 aggregate limit for violations arising from the same transaction documentation or materials. Following written notice of a prior violation, the statute authorizes $1,000 per violation and a $50,000 aggregate cap.
Most importantly for contract-risk analysis, Georgia expressly says:
- the section creates no private right of action based on noncompliance; and
- a violation does not affect enforceability of the underlying agreement.
Connecticut Commercial Financing Registration and Broker Rules
Yes. Connecticut currently requires both covered commercial financing brokers and providers to register with the Banking Commissioner.
Any 2026 discussion of commercial finance broker registration requirements by state that says only Virginia expressly registers brokers is outdated. Connecticut’s Department of Banking states directly that it has two types of commercial financing registration: one for providers and one for brokers.
What Connecticut Covers
Under Connecticut’s current effective statute, “commercial financing” means an extension of sales-based financing by a provider in an amount not exceeding $250,000, where the proceeds are not intended primarily for personal, family or household purposes.
A “commercial financing broker” is generally a person other than a financer that, for compensation or expected compensation, offers or offers to obtain covered financing for a recipient from a nonexempt provider.
Connecticut therefore does not use “commercial financing” as a blanket term for every business loan under this particular registration statute.
Registration Deadline and NMLS
The law required providers and commercial financing brokers to register no later than October 1, 2024.
The current Connecticut commercial financing law registration process is administered by the Connecticut Department of Banking through NMLS. An existing NMLS company generally submits the company MU1 and applicable control-person MU2 records and satisfies Connecticut’s jurisdiction-specific requirements.
2025 Amendment Changed the Renewal System
This is an area where older articles can produce the wrong answer.
Connecticut Public Act 25-115 replaced the former September 15 annual-fee model. Effective July 1, 2025, a registration generally expires at the close of business on December 31 of the year in which it was approved. A registration approved on or after November 1 generally runs through December 31 of the following year.
Renewal applications must be filed between November 1 and December 31 of the expiration year. Initial and renewal applicants pay $1,000 plus applicable system charges, and those fees are nonrefundable.
That makes Connecticut commercial financing law registration materially different in 2026 from its original 2024 renewal structure.
Connecticut Is Actively Enforcing Registration
The requirement is not theoretical.
In June 2026, the Department of Banking announced a consent order involving alleged commercial-financing activity without required registration; the respondent paid a $10,000 civil penalty and $2,000 in back registration fees.
In September 2026, another consent order alleged 74 agreements had been entered into without required registration; that matter included a $10,000 civil penalty and $1,000 in back registration fees. These are specific consent orders, not universal penalty schedules for every case.
Current §36a-872 also authorizes the commissioner to suspend, revoke or refuse renewal and to exercise the Banking Commissioner’s statutory enforcement powers for violations.
Connecticut brokers should verify both the legal requirement and the filing status before submitting covered sales-based financing. The Department of Banking’s commercial financing provider and broker registration instructions explain the NMLS filing process, while the Department’s registered providers and brokers page can be used to confirm current authorization.
Because Connecticut amended its renewal structure after the original law took effect, renewal timing should also be checked against the current Connecticut commercial-financing statutes rather than relying on older implementation articles.
New York CFDL: Provider Disclosures and Broker Responsibilities
New York’s Commercial Finance Disclosure Law does not create a separate statewide MCA broker license. It does, however, directly regulate a broker’s handling of specific offers and disclosures.
New York Financial Services Law Article 8 covers commercial financing including closed-end financing, open-end financing, sales-based financing, factoring and other covered business-purpose financing.
The amount exemption currently excludes an individual commercial financing transaction over $2.5 million. Other exemptions include financial institutions, certain technology providers serving exempt institutions, Farm Credit lenders, real-property-secured transactions, UCC leases, persons or providers making no more than five covered transactions in New York in 12 months, and specified dealer or rental-company financing.
Who Is the Provider?
The statute’s “provider” definition is broader than “funder.”
A provider is a person extending a specific offer of commercial financing and, unless exempt, can include a person that solicits and presents specific offers on behalf of a third party. New York therefore cannot be analyzed simply by applying industry job titles.
Do the CFDL License Brokers?
No. The CFDL itself does not establish an occupational commercial financing broker license or CFDL registration.
That answer must be separated from two other questions: whether another New York licensing law independently applies to the activity, and whether the broker has responsibilities under the CFDL regulations.
Brokers Have Direct Part 600 Duties
23 NYCRR §600.21 requires a financer that uses a broker to give the broker compliant disclosures.
The broker, before communicating the specific commercial financing offer, must transmit the unaltered disclosure to the recipient and then return evidence of transmission, including the time of transmission, to the financer.
So the accurate New York answer is neither “brokers are licensed under the CFDL” nor “brokers have no CFDL responsibilities.”
Misquoting Rates Creates Additional Risk
Financial Services Law §810 restricts how financing cost metrics may be described. A metric cannot be presented as a “rate” if it is not an annual interest rate or APR, and the statute imposes specific APR terminology rules when a provider states certain cost metrics during the application process.
Violations by a statutory provider may result in civil penalties of up to $2,000 per violation, or $10,000 for a willful violation. For knowing violations, the Superintendent may order additional relief including restitution or injunctive relief.
California SB 1235: Provider Duties, Broker Communications, and Separate Licensing Questions
California SB 1235 does not create a general commercial-finance broker registration requirement for 2026. Separate California Financing Law licensing can nevertheless apply depending on the activity and financing structure.
SB 1235’s current commercial-financing disclosure system is administered by the Department of Financial Protection and Innovation. DFPI states that the regime requires a provider extending a specific commercial-financing offer to give prescribed disclosures to the recipient, and the recipient must sign before the transaction is finalized.
What Transactions Are Covered?
California’s commercial-financing disclosure framework reaches specific offers up to $500,000.
DFPI identifies covered financing as including:
- accounts-receivable purchase transactions, including merchant cash advances;
- asset-based lending;
- qualifying commercial loans;
- commercial open-end credit plans; and
- Lease financing.
The final implementing regulations became effective December 9, 2022.
The Broker’s Role
California’s regulations distinguish the financer from the intermediary broker.
Under the broker-handling framework in 10 CCR §952, a financer working through a broker supplies the required disclosure and the broker must transmit it at the required point in the offer process. DFPI’s final rulemaking explanation states that the broker is obliged to communicate compliant disclosures before extending the relevant specific offer.
The rulemaking record also draws a useful liability distinction: an intermediary is not automatically responsible merely because a financer supplied a defective disclosure, but that does not insulate a broker from its own representations concerning the financing.
That is a central difference when comparing CFDL SB 1235 broker obligations. New York and California both use provider/financer-generated disclosure systems with meaningful intermediary transmission controls, but neither disclosure regime should simply be labeled an “MCA broker license.”
Separate California Financing Law Licensing
The California Financing Law already regulates persons in the business of making or brokering loans. Whether that law applies depends on what the business actually does and how the transaction is legally characterized.
A true accounts-receivable purchase should therefore not automatically be labeled a “loan” solely because it is commercially described as an MCA. Conversely, calling a transaction an MCA does not determine its legal classification if its actual structure falls within another regulated category.
Major 2026 Update: AB 2116
On September 30, 2026, California enacted AB 2116.
The newly enacted law will broadly bring commercial financing providers and commercial financing brokers into the California Financing Law framework beginning in 2028.
The enacted measure provides for broader regulation beginning January 1, 2028, with the prohibition on engaging in business as a commercial financing provider or commercial financing broker without the required license beginning July 1, 2028.
This is a future compliance project—not a reason to write that every California MCA broker needs the new AB 2116 license in 2026.
That future change should nevertheless be placed on any multistate brokerage’s regulatory calendar now.
State-by-State Transaction Limits and Exemptions
The transaction threshold is one of the easiest places to make a costly error when applying commercial finance broker registration requirements by state.
| State | Current Amount Rule | Financial-Institution Exemption | Real-Estate-Secured | Lease / Purchase-Money | De Minimis | Other Important Exemptions |
| Virginia | Single SBF transaction over $500,000 exempt | Yes | Chapter is SBF-specific | Not a generalized list like Utah/Georgia | ≤5 transactions with a recipient / 12 months | Statute is narrowly structured around sales-based financing |
| Utah | Transaction over $1 million exempt | Yes | Yes | Both | ≤5 products / 12 months | Farm Credit, money transmitter, specified dealers/seller-connected financing |
| Georgia | Transaction over $500,000 exempt | Yes | Yes | Both | Provider/de minimis exemption | Healthcare receivables, dealer and seller-connected financing |
| Connecticut | Current covered SBF ≤$250,000 | Yes | Yes | Both | Specified five-or-fewer exemption | Farm Credit and other statutory exclusions |
| New York | Transaction over $2.5 million exempt | Yes | Yes | Lease exempt | ≤5 / 12 months | Certain technology-provider and dealer exemptions |
| California | Specific offer ≤$500,000 within disclosure regime | Yes | Yes | Statutory product-specific exclusions | Limited-transaction exemptions apply | Farm Credit and qualifying dealer transactions |
Do not reuse one state’s exemption checklist for another. Virginia’s unusual “five transactions with a recipient” language, for example, should not be replaced with Utah’s or New York’s differently structured de minimis tests.
Provider-Only vs. Broker-Registration Regimes
If a state has a commercial financing disclosure law, does that mean the broker needs a license?
No. A commercial financing disclosure statute and a broker-registration statute regulate different things. The statutory definitions and operative registration provisions—not the existence of a disclosure law—determine whether the broker must register.
Virginia and Connecticut expressly require covered brokers to register.
Utah defines “broker,” but its commercial-financing registration requirement is written for persons conducting covered transactions as providers.
Georgia regulates broker conduct without creating a §10-1-393.18 broker license.
New York’s CFDL creates disclosure and broker-transmission responsibilities but does not create a separate CFDL broker license.
California’s SB 1235 similarly regulates transaction disclosures and broker handling of disclosures without creating the new, broader commercial-financing license that AB 2116 will require beginning in 2028.
This provider-versus-broker distinction is one of the most important principles in commercial finance broker registration requirements by state.
How Commercial Finance Registration Works in Practice
A brokerage should treat commercial finance broker registration requirements by state as a pre-submission control rather than a problem to investigate after underwriting.
1. Determine the Company’s Statutory Role
Do not rely only on labels such as “ISO,” “broker,” “marketplace,” “consultant” or “funder.”
Compare the company’s actual conduct with each state’s definitions of broker, provider, financer and recipient.
2. Determine the Recipient’s Location
State statutes use different jurisdictional triggers.
Virginia focuses on the recipient’s principal place of business. Utah reaches covered provider activity in Utah or with a Utah resident. Georgia’s broker definition expressly references communicating a binding third-party offer to a business located in Georgia.
Record the legal location evidence in the deal file.
3. Classify the Financing Product
Determine whether the transaction is:
- sales-based financing;
- a commercial loan;
- open-end financing;
- factoring;
- an accounts-receivable purchase;
- asset-based financing;
- lease financing; or
- another product.
“MCA” is a market description, not a universal statutory classification.
4. Record the Transaction Amount
Apply the correct state’s measurement methodology and threshold.
Never assume $500,000 is a national commercial-financing cutoff.
5. Test Every Statutory Exemption
Document the specific exemption, not simply “exempt.”
If relying on a de minimis exception, preserve the transaction-count data used to support it.
6. Identify the Filing System
Current filing paths include:
- Virginia: SCC registration;
- Utah: DFI registration through NMLS;
- Connecticut: Department of Banking registration through NMLS.
Georgia and New York do not create the comparable broker-registration filing under the disclosure statutes discussed above. California SB 1235 does not create that filing either for 2026.
7. Collect Entity and Control Information
Where required, maintain:
- exact legal entity name;
- DBA names;
- principal office address;
- formation jurisdiction;
- foreign qualification;
- control-person details;
- regulatory actions;
- criminal-history disclosures; and
- designated agent information.
8. Check Registered-Agent and Bond Requirements Individually
Do not insert a generic surety-bond requirement into a commercial financing compliance checklist.
For example, Utah requires information concerning a Utah designated agent for service in its statutory registration statement. A bond should not be added to the checklist unless the applicable law or current filing requirements actually require one.
9. Record Fees and Expiration Dates
The fee belongs to the specific authorization.
NMLS system charges should not be confused with the state’s statutory registration fee.
10. Verify Active Status Before Submission
Use the regulator or NMLS Consumer Access where applicable and save evidence of the verification.
NMLS is a filing system, not a nationwide commercial financing license.
What Happens If You Place a Deal Without Required Registration?
There is no universal answer.
The correct consequence under commercial finance broker registration requirements by state depends on the particular statute and the conduct involved.
Virginia
A registration can expire automatically for failure to pay the annual fee. The Attorney General may seek injunctive and other authorized relief.
Virginia also says a provision of an agreement violating Chapter 22.1 is unenforceable against the recipient. That is narrower and more accurate than saying “every unregistered Virginia MCA is automatically void.”
Utah
Utah permits administrative and judicial enforcement and specified civil penalties.
But Utah expressly states that its chapter does not create a private right of action and that a violation does not affect the enforceability of the underlying agreement.
Georgia
Georgia likewise provides public enforcement and civil penalties while expressly disclaiming a private right of action under §10-1-393.18 and preserving the underlying agreement’s enforceability.
Connecticut
Connecticut may suspend, revoke or refuse to renew registration and use its general Banking Commissioner enforcement powers. Current 2026 consent orders demonstrate that the Department is investigating unregistered commercial-financing activity.
New York and California
The central statutes discussed here are disclosure regimes, so the relevant enforcement question is usually whether the provider or broker violated a transaction-level duty rather than whether the broker lacked a CFDL/SB 1235 registration that does not exist.
Separate licensing laws can produce different consequences when independently applicable.
Provider Disclosure Duty Does Not Protect a Broker From a Misquote
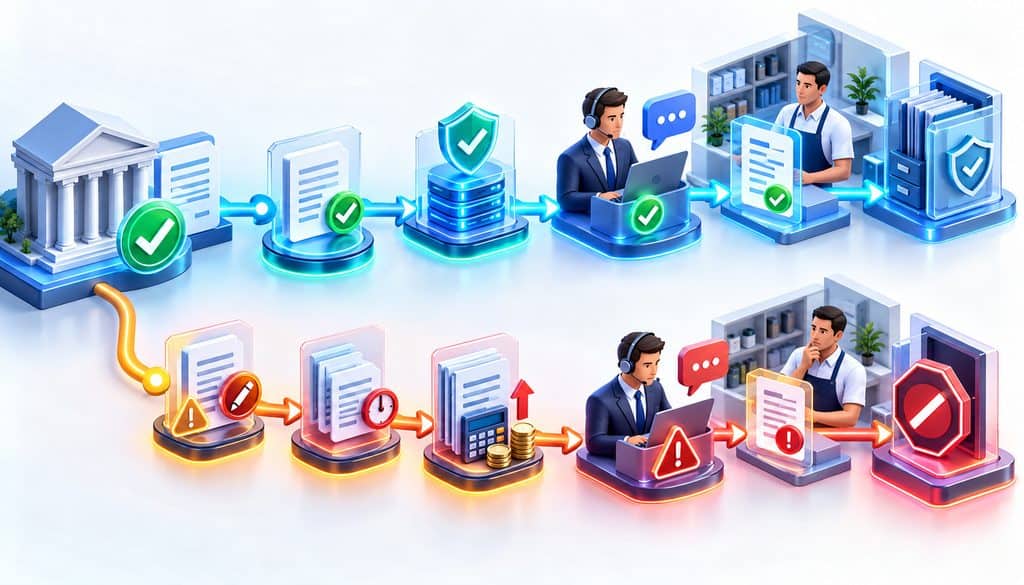
A broker should never interpret “the provider generates the disclosure” as permission to communicate different economics.
This is especially important when evaluating CFDL SB 1235 broker obligations.
New York requires a broker to transmit the financer-provided disclosure unaltered before communicating the specific offer. California’s regulatory framework similarly places the broker between the financer-generated disclosure and the recipient.
Potential problems include:
- describing a factor rate as an APR;
- understating expected daily or weekly payments;
- promising an early-payoff discount that is not in the approved offer;
- changing terms supplied by the provider;
- promising approval;
- sending an old disclosure after terms changed;
- quoting one repayment amount orally while the approved disclosure states another.
A brokerage should use the provider-approved disclosure as the reference point for every email, CRM note, comparison sheet, and verbal explanation. A separate broker disclosure-compliance workflow can help prevent pricing misquotes, outdated offer terms, and inconsistent communications, but the legal standard still comes from the applicable state statute and regulations.
In New York, 23 NYCRR §600.21 requires an intermediary broker to transmit the financer-provided disclosure unaltered before communicating the specific offer. California’s DFPI likewise explains broker handling of financer-generated disclosures in its commercial-financing disclosure rulemaking record.
Per-Deal Broker Registration and Disclosure Check Before Submission
A brokerage can convert commercial finance broker registration requirements by state into a repeatable workflow:
- Identify the merchant’s legal business location. Save the application, formation information or written location representation used.
- Identify the financing recipient. Make sure the legal recipient and the sales contact are not being confused.
- Classify the product. Loan, open-end credit, MCA/sales-based financing, factoring, receivables purchase, lease or other.
- Record the financing amount.
- Check the applicable state’s transaction threshold.
- Test every relevant statutory exemption.
- Verify the broker’s registration where required.
- Verify the provider’s registration or license where required.
- Match the application only with providers authorized for the transaction and jurisdiction.
- Determine who generates the statutory disclosure.
- Do not independently rewrite or alter a provider-approved disclosure.
- Save registration verification and disclosure-delivery evidence.
- Calendar registration renewal and expiration dates.
- Stop the submission if required authorization cannot be verified.
Broker Compliance Matrix
| Question | Yes / No | Evidence to Save |
| Is the merchant in a regulated jurisdiction? | Application/address evidence | |
| Is the financing product covered? | Product classification memo | |
| Is the transaction within the statutory amount range? | Offer/funding amount | |
| Is broker registration active where required? | Regulator or NMLS verification | |
| Is provider registration/license active where required? | Regulator or NMLS verification | |
| Has any exemption been documented? | Statutory citation + supporting records | |
| Has the correct party generated the disclosure? | Final disclosure copy | |
| Do email and verbal quotes match approved terms? | CRM/email record | |
| Has proof of transmission/signature been retained? | Timestamp, signature or transmission record |
Three Real-World Compliance Examples
Example 1 — Virginia MCA Submission
A broker receives an application from a business whose principal place of business is Virginia for $175,000 in financing tied to future sales.
Before submitting, the brokerage should determine whether the structure satisfies Virginia’s sales-based financing definition, check the statutory exemptions, verify its own Virginia registration and the provider’s registration, and confirm that the provider will issue the required disclosure.
The funder’s registration does not replace the broker’s registration.
Example 2 — New York Broker Quote
A broker tells a New York business that a proposed transaction will have particular pricing before the financer has finalized the specific offer.
Once a covered specific offer exists and the financer provides the Part 600 disclosure, the broker must transmit that disclosure unaltered before communicating that specific offer. New York does not need to create a separate CFDL broker license for that broker-transmission rule to apply.
Example 3 — Multistate Brokerage
A brokerage headquartered in Florida accepts applications from businesses in Virginia, Utah, Connecticut, California and New York.
Its Florida headquarters do not answer the compliance question.
For each application, the brokerage should determine the recipient-state jurisdiction, product, amount and exemption status, then apply the relevant state authorization rules. That could mean Virginia broker registration, Connecticut broker registration, Utah provider-status analysis, New York Part 600 transmission controls and California SB 1235 disclosure handling.
2026 Registration Renewal Calendar
| State | Initial Filing | Renewal Frequency | Renewal Window / Deadline | Regulator / System |
| Virginia | Before conducting covered activity | Annual | State annual fee by Sept. 15 | Virginia SCC |
| Utah | Before acting as a covered provider | Annual | Registration expires Dec. 31 | Utah DFI / NMLS |
| Georgia | Not applicable under §10-1-393.18 | N/A | Not applicable under this statute | Georgia AG enforcement framework |
| Connecticut | Before covered activity; initial statutory deadline was Oct. 1, 2024 | Annual | Nov. 1–Dec. 31 of expiration year | CT DOB / NMLS |
| New York | Not applicable under CFDL | N/A | Not applicable under CFDL | NYDFS |
| California | Not applicable under SB 1235 | N/A | Not applicable under SB 1235 | DFPI; separate CFL analysis where relevant |
For Utah, the statutory registration expires December 31. DFI’s current filing instructions should be checked each renewal season for the operative NMLS submission process and any system charges.
Common Commercial Finance Broker Compliance Mistakes
A useful internal review of commercial finance broker registration requirements by state should flag these recurring problems:
- assuming every disclosure state licenses brokers;
- assuming every MCA is legally classified the same way;
- relying on the broker’s headquarters instead of the statutory jurisdiction test;
- treating provider authorization as authorization for the broker;
- applying one state’s transaction cap to another;
- relying on an old Connecticut September renewal date;
- calling NMLS registration a nationwide license;
- using an expired registration screenshot;
- assuming broker disclosure duties disappear because the provider creates the form;
- modifying provider pricing before sending it to the merchant;
- failing to document why an exemption applies; and
- assuming registration failure automatically voids the financing agreement.
A strong compliance file should explain why the transaction was considered covered, exempt or outside the statute—not merely record a checkbox.
FAQs
Do MCA brokers have to be licensed in every state?
No. Commercial finance broker registration requirements by state depend on the jurisdiction, the broker’s actual conduct, the product, transaction amount and statutory exemptions.
Some jurisdictions require broker registration, while others regulate providers or impose disclosure and broker-conduct rules without creating a standalone commercial financing broker license.
Which states require sales-based financing brokers to register in 2026?
Among the six states covered here, Virginia and Connecticut expressly register covered brokers. Utah defines brokers but Chapter 27’s registration mandate applies to covered providers. Georgia, New York’s CFDL and California’s SB 1235 do not create the same general broker registration.
Does a Virginia MCA broker need to register?
Yes, when the broker conducts covered, nonexempt sales-based financing activity.
Virginia Code §6.2-2230 expressly requires both providers and brokers to register with the State Corporation Commission. The initial fee is $1,000 and the annual $500 fee is due September 15.
Does Utah require commercial financing brokers to register with the DFI?
Not merely because the entity is a broker.
Utah §7-27-201 requires registration before engaging in covered commercial financing transactions as a provider. A broker whose actual operations separately make it a statutory provider must register on that basis.
Does Georgia require commercial financing brokers to be licensed?
Not under O.C.G.A. §10-1-393.18.
The statute regulates disclosures and directly prohibits specified broker conduct, but it does not create a general commercial-finance broker registration program.
Does Connecticut require commercial financing broker registration?
Yes.
The Connecticut Department of Banking expressly maintains separate provider and broker registrations. The current Connecticut commercial financing law registration is filed through NMLS and generally renews between November 1 and December 31.
Does New York’s Commercial Finance Disclosure Law license MCA brokers?
No. The CFDL does not create a standalone MCA broker license.
However, 23 NYCRR §600.21 requires an intermediary broker to transmit the financer-provided disclosure unaltered before communicating a specific covered offer and provide evidence of transmission to the financer.
Does California SB 1235 require MCA brokers to hold a license?
Not under SB 1235 itself in 2026.
Separate California Financing Law licensing can apply to activities already regulated by that law. In addition, AB 2116 was signed September 30, 2026 and establishes broader commercial-financing licensing beginning in 2028, with the new licensing prohibition scheduled for July 1, 2028.
What happens if I broker a commercial financing transaction while unregistered?
It depends on the governing statute.
Consequences can include administrative action, civil penalties, suspension or revocation, injunctions, registration problems and provider rejection of a submission. Contract unenforceability or a private lawsuit should never be assumed without checking the particular statute.
Final Takeaway
The safest way to apply commercial finance broker registration requirements by state is to stop thinking of commercial-financing regulation as one nationwide rule.
Virginia expressly registers covered sales-based financing brokers and providers. Connecticut separately registers brokers and providers through NMLS. Utah’s registration requirement is tied to provider status rather than broker status alone. Georgia imposes commercial-financing disclosures and broker-conduct restrictions without establishing a §10-1-393.18 broker license.
New York’s CFDL creates provider disclosure and direct broker-transmission duties without creating a separate CFDL broker license. California’s SB 1235 follows a similar disclosure model in 2026, while AB 2116 now creates a major new licensing framework beginning in 2028.
For every submission, identify the recipient’s jurisdiction, classify the financing product, apply the correct transaction threshold, test exemptions, verify the broker and provider authorization separately, identify who generates and transmits the disclosure, and preserve evidence of every determination.
That workflow turns commercial finance broker registration requirements by state from a vague licensing question into a documented per-deal compliance control. Because amendments, regulatory procedures and filing fees can change, a brokerage should recheck the current statute, regulator guidance and NMLS/state filing instructions whenever a new jurisdiction or unusual product structure is involved.