By Jonathan Price October 3, 2026
A reverse consolidation merchant cash advance generally does not pay off stacked MCAs. Instead, a new provider supplies scheduled capital that helps offset existing remittances while the merchant assumes a separate repayment obligation. This can reduce immediate cash pressure, but the underlying positions remain and the merchant’s total layered contractual repayment can increase.
For a merchant already losing thousands of dollars each week to stacked merchant cash advances, that distinction is critical. Reverse consolidation can solve a timing and liquidity problem without necessarily solving the underlying financing-cost problem.
The right analysis therefore has two parts: How much cash does the arrangement free today, and how many total dollars will leave the business before every position is finished?
Reverse Consolidation vs. True MCA Consolidation Payoff
| Issue | Reverse Consolidation | True Consolidation / Refinance |
| Existing MCA positions | Generally remain outstanding | Specified positions are usually paid off |
| Existing payments | Continue according to existing contracts | Usually stop after confirmed payoff |
| New capital | Often released periodically to help carry existing payments | Primarily used to retire existing positions |
| New obligation | Added alongside existing contracts | Replacement obligation |
| Immediate cash-flow relief | Can be substantial during supported weeks | Depends on replacement terms |
| Position count | May temporarily increase | Usually decreases |
| Total layered cost | Can increase materially | Depends on payoff quotes and replacement financing |
| Contract-consent risk | Potentially significant | Payoff and consent provisions still require review |
| Best comparison | Full remaining cost of old positions plus new RC | Total replacement cost after payoffs |
| Payoff letters | Useful for analysis | Usually essential to closing accurately |
Deal structures vary. “Reverse consolidation” is a market description, not a guarantee that every provider uses the same contract, funding schedule, payment method, or legal structure.
How a Reverse Consolidation Merchant Cash Advance Actually Works
A reverse consolidation merchant cash advance is best understood as a cash-flow bridge layered around existing financing rather than as an automatic payoff.
Assume a business has three MCA positions. All three continue taking contractual daily ACH withdrawals or weekly remittances.
A reverse-consolidation provider may commit new capital but release it in scheduled installments rather than paying the existing funders in full. The merchant simultaneously becomes responsible for repayment under the new agreement.
A simplified flow is:
Merchant revenue → Existing MCA remittances continue → Reverse-consolidation provider releases scheduled support → Merchant separately repays new provider
That is why an accurate MCA reverse consolidation explained in plain English must distinguish four different transactions:
- Reverse consolidation: scheduled new funding helps carry existing payments while those positions generally remain open.
- True MCA consolidation payoff: replacement proceeds retire identified existing positions.
- Term-loan refinance: qualifying obligations are paid with proceeds from conventional replacement credit.
- Payment modification: an existing provider agrees to change its own remittance or other payment terms.
A proposal should be evaluated by its actual contract rather than its label. A product marketed as reverse consolidation is not necessarily structured legally as another MCA, and an agreement called an MCA is not automatically treated as a true receivables purchase in every jurisdiction.
That distinction can matter in litigation. In the February 19, 2026 New York appellate decision People v. Richmond Capital Group LLC, the court upheld the characterization of the transactions before it as loans after examining how the agreements actually operated, including reconciliation and fixed-payment characteristics. The decision is transaction-specific and does not establish that every MCA is a loan.
That last distinction is not theoretical. In February 2026, the New York Appellate Division affirmed that transactions in People v. Richmond Capital Group that were styled as MCAs were properly characterized as loans based on how the agreements operated.
The court emphasized facts including reconciliation that was not actually performed, fixed payments unrelated to a good-faith estimate of receivables, and recourse characteristics.
Earlier New York decisions likewise analyze substance rather than simply accepting the MCA label.
This does not establish a nationwide rule that MCAs are loans. It shows why legal characterization depends on governing law, contractual terms, and actual operation.
How the Reverse Consolidation Weekly Payment Works
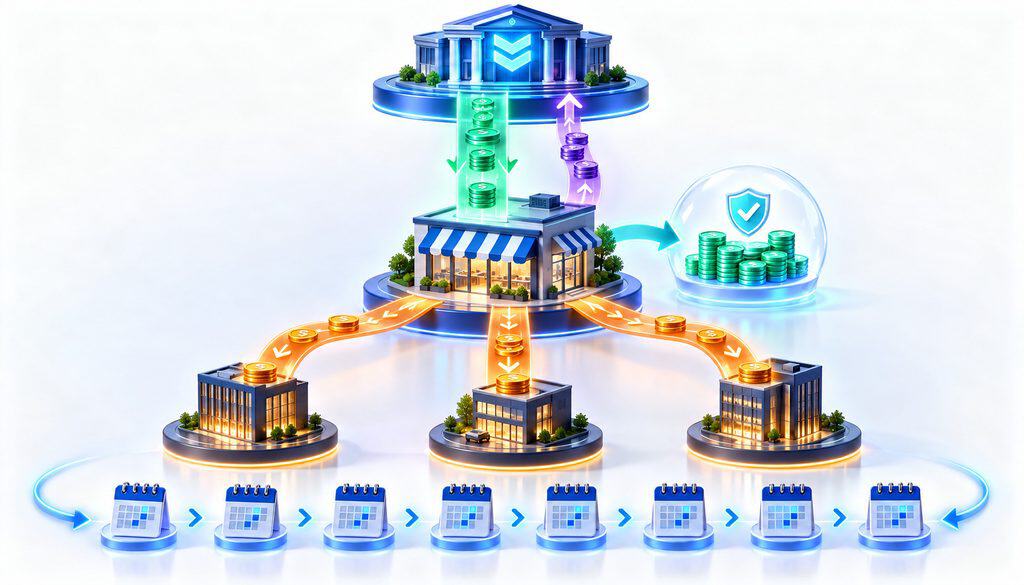
Consider a business with three existing positions.
Illustrative numbers only — not industry averages or quoted market terms.
| Position | Existing Weekly Remittance |
| MCA A | $3,000 |
| MCA B | $2,200 |
| MCA C | $1,800 |
| Total | $7,000 |
Assume a hypothetical reverse consolidation merchant cash advance commits $50,000 and releases $5,000 each week for 10 weeks.
For illustration, assume the new agreement has a $70,000 contractual payback and requires $2,000 per week.
The first eight weeks would look like this:
| Week | Existing MCA Payments | RC Advance Received | RC Repayment | Merchant’s Immediate Net Cash Burden | RC Payback Remaining After Payment |
| 1 | $7,000 | $5,000 | $2,000 | $4,000 | $68,000 |
| 2 | $7,000 | $5,000 | $2,000 | $4,000 | $66,000 |
| 3 | $7,000 | $5,000 | $2,000 | $4,000 | $64,000 |
| 4 | $7,000 | $5,000 | $2,000 | $4,000 | $62,000 |
| 5 | $7,000 | $5,000 | $2,000 | $4,000 | $60,000 |
| 6 | $7,000 | $5,000 | $2,000 | $4,000 | $58,000 |
| 7 | $7,000 | $5,000 | $2,000 | $4,000 | $56,000 |
| 8 | $7,000 | $5,000 | $2,000 | $4,000 | $54,000 |
During each supported week:
$7,000 existing payments + $2,000 RC payment − $5,000 new funding = $4,000 immediate net cash burden
Compared with the original $7,000 weekly burden, the merchant temporarily supplies $3,000 less of its own cash.
That is genuine stacked MCA payment relief in a cash-flow sense.
It is not $3,000 of debt forgiveness, a $3,000 reduction in remaining purchased amount, or $3,000 of financing-cost savings. New outside capital is supplying the difference.
Once the scheduled advances end, the merchant may still owe the reverse-consolidation provider. Whether existing positions have matured by then determines what the later cash-flow burden looks like.
The Real Cost of Reverse Consolidation: Add the New Payback to Existing Paybacks
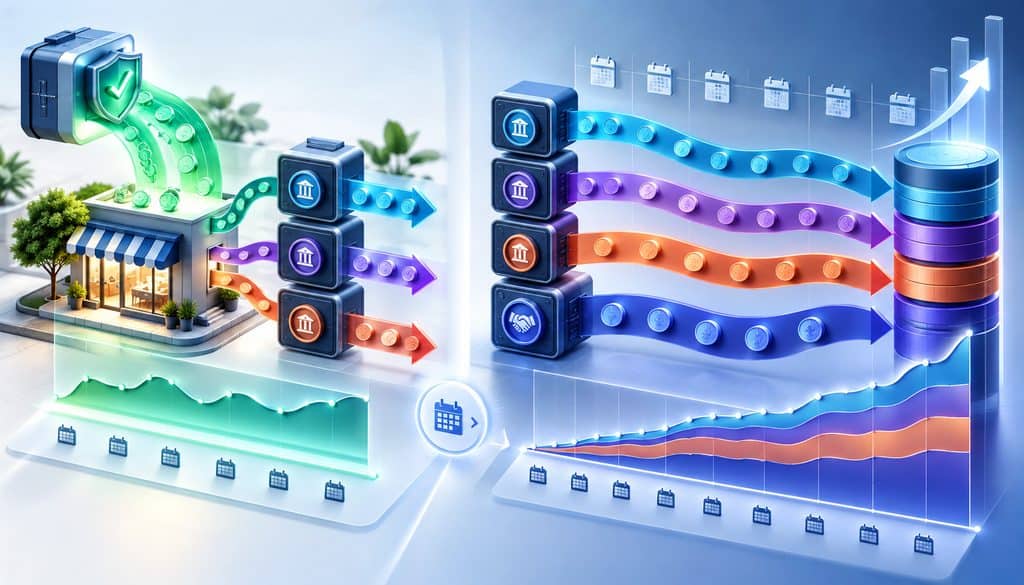
The most important number in a reverse consolidation merchant cash advance proposal is not the advertised weekly relief.
It is the total contractual dollars remaining across every position.
Suppose the merchant currently has $105,000 of remaining contractual payback across three MCAs.
Now assume the reverse-consolidation agreement commits $50,000 at an illustrative factor of 1.40.
The contractual payback is:
$50,000 × 1.40 = $70,000
The resulting layered calculation becomes:
| Component | Amount |
| Remaining contractual payback on existing positions | $105,000 |
| New RC contractual payback | $70,000 |
| Combined contractual dollars potentially payable | $175,000 |
The $20,000 difference between $50,000 advanced and $70,000 of contractual payback should not automatically be called “interest.” MCA agreements are frequently drafted as purchases of future receivables rather than conventional loans. Whether a particular agreement is legally respected as such depends on applicable law and its substance.
Likewise, a factor of 1.40 should not casually be converted into an APR. A factor is a multiplier, while APR is an annualized cost measurement requiring timing and cash-flow assumptions.
The full-cost formula
Combined Remaining Dollar Obligation = Remaining Contractual Payback on Existing Positions + Contractual Payback on New Reverse-Consolidation Position + Applicable Contractual Fees
The merchant should identify separately any disclosed or contractually permitted:
- origination charges;
- broker compensation;
- ACH charges;
- documentation or legal charges;
- modification charges;
- payoff premiums;
- default-related charges; or
- other deductions.
There is no reliable universal percentage that should be assumed for these items.
The fundamental rule is:
Immediate Cash-Flow Relief ≠ Total-Dollar Savings
The distinction between usable proceeds, financing cost, payment obligations, and other transaction terms also matters when commercial-financing disclosure requirements apply to brokered funding offers. Applicable requirements vary by jurisdiction and transaction, so state-specific legal claims should be checked against the relevant regulator or statute.
That distinction is also consistent with the direction of commercial-financing disclosure regulation. California, for example, requires covered providers extending specific commercial-financing offers to disclose information including funds provided, total dollar cost, term or estimated term, payment method/frequency/amount, and prepayment policies. DFPI’s regulations expressly contain disclosure rules for sales-based financing and became effective December 9, 2022.
Those disclosure requirements should not be confused with the separate legal question of whether a particular transaction is a loan or a bona fide receivables purchase.
California is one example: the state’s commercial-financing disclosure rules expressly address covered commercial financing, including sales-based financing. Those disclosure requirements should not be interpreted as establishing a nationwide rule about whether every MCA or reverse consolidation merchant cash advance is legally a loan.
Why Stacked MCA Payment Relief Can Be Valuable Early
A business can generate enough gross profit to remain viable before financing withdrawals but still face a severe liquidity squeeze after multiple daily ACH withdrawals.
That explains the appeal of a reverse consolidation merchant cash advance.
Scheduled outside funding can potentially leave more operating cash available for payroll, inventory, rent, taxes, essential suppliers, or other expenses while shorter-duration positions age.
The benefit depends on several things happening as modeled:
- scheduled funding continues;
- sales remain sufficient;
- existing positions eventually mature;
- the merchant avoids further MCA stacking;
- existing providers do not trigger contractual remedies; and
- the new repayment remains affordable after support ends.
A reverse consolidation that simply allows a merchant to add another stack later has not necessarily reduced the underlying cash-flow burden.
Why the Cash-Flow Curve Changes Over Time
A reverse consolidation weekly payment cannot be evaluated accurately from the first few weeks alone.
Early in the transaction, existing MCA withdrawals may be at their highest while RC funding support is also at its highest. Later, older positions may mature—but scheduled support may also end while RC repayment continues.
| Stage | Existing MCA Burden | RC Funding | RC Repayment | Cash-Flow Effect |
| Early weeks | High | High | Begins/continues | Relief can be strongest |
| Middle period | May decline | Continues per agreement | Continues | Depends on positions aging off |
| Older positions mature | Lower | May decline/end | Continues | Residual RC burden matters more |
| Final RC period | Some/all old positions may be gone | None | May continue | Longer payment tail can remain |
This is a conceptual model, not a standard reverse-consolidation schedule.
A merchant trying to consolidate stacked merchant cash advances should therefore model every week until the last projected payment rather than compare today’s debits with only next week’s proposed net burden.
Can a Reverse Consolidation Violate an Existing MCA Agreement?
Potentially. Whether a reverse consolidation merchant cash advance breaches an existing agreement depends on the wording of that agreement and the structure of the new transaction.
Not every MCA contains a provision literally called an “anti-stacking clause.”
Instead, contracts may contain restrictions or covenants concerning:
- obtaining additional financing;
- selling or assigning additional receivables;
- granting competing security interests;
- changing a designated deposit account;
- diverting receivables;
- interfering with ACH or processor instructions;
- representations concerning existing financing;
- notice or consent requirements; or
- material changes affecting the business.
Suppose Position A states that another sale of receivables requires consent. Adding a new receivables-purchase position could potentially create a contractual default even though the merchant’s objective was to obtain payment relief.
Cross-default can connect separate agreements
A cross-default provision can make a default under one obligation relevant to another agreement.
That does not mean every MCA contains cross-default language or that every additional financing transaction automatically causes default. The documents must be reviewed individually.
Before adding another position, examine:
- additional-financing restrictions;
- additional receivables-sale provisions;
- cross-default provisions;
- security-interest language;
- UCC provisions;
- designated bank-account covenants;
- notice and consent requirements;
- reconciliation language;
- personal-guarantee triggers; and
- default and remedy provisions.
When compatibility is uncertain, qualified counsel should review the actual agreements rather than relying on a broker’s description of the clauses.
UCC Filings Can Reveal Financing—but Not What the Merchant Owes
Existing positions may become visible during underwriting through bank statements, ACH withdrawals, merchant-supplied agreements, payoff statements, processor activity, business and credit information, and UCC financing-statement searches where applicable.
A UCC financing statement is not a payoff letter.
The New York Department of State explains that a UCC-1 financing statement provides notice that a creditor claims a security interest in a debtor’s personal property and is not itself the underlying agreement. A filing can therefore help identify a potential secured party without establishing the merchant’s current remaining purchased amount or payoff figure.
Article 9 permits a financing statement meeting the statutory requirements to identify the debtor, secured party or representative, and collateral. Filing and attachment are separate concepts; a financing statement can in certain circumstances be filed before the security interest attaches.
Accordingly, a UCC record can provide notice of a claimed security interest, but it does not establish the merchant’s current remaining purchased amount, current payoff quote, contractual early-payoff discount, or exact amount needed to close an MCA.
That distinction matters when comparing reverse consolidation vs MCA consolidation loan economics. Use current payoff letters or other contractually operative payoff information, not the face of a UCC filing, to calculate a consolidation payoff.
Where merchantcapitalbrokers.com publishes a dedicated informational guide explaining how MCA stacking appears through bank activity and UCC searches, that article is the natural internal link here. The present article addresses a different question: what the exit structure costs once the merchant is already stacked.
What Underwriters Look at Before Offering Reverse Consolidation
There is no universal statutory underwriting formula for a reverse consolidation merchant cash advance, nor is there a standardized legal maximum number of MCA positions that can qualify.
Provider underwriting can consider:
- number of existing positions;
- original funded amounts;
- remaining purchased amounts or payoff balances;
- daily and weekly remittances;
- average monthly deposits;
- deposit consistency;
- months in business;
- overdrafts and negative days;
- NSFs and returned ACHs;
- recent MCA stacking;
- declining revenue;
- industry;
- UCC filings;
- existing defaults;
- payment modifications;
- collections or charge-offs;
- payment history; and
- projected remaining duration of each position.
One useful analytical measurement is:
Existing MCA Payment Load = Total Scheduled MCA Remittances During the Measurement Period ÷ Gross Business Revenue During the Same Period
If a hypothetical business makes $30,000 of MCA payments during a month in which gross business revenue is $120,000:
$30,000 ÷ $120,000 = 25%
That 25% is merely a descriptive ratio. It is not a universal approval threshold.
No authoritative nationwide rule establishes a standard reverse-consolidation payment-load limit. Providers set their own underwriting tolerances, subject to applicable law.
Reverse Consolidation vs MCA Consolidation Loan or True Payoff
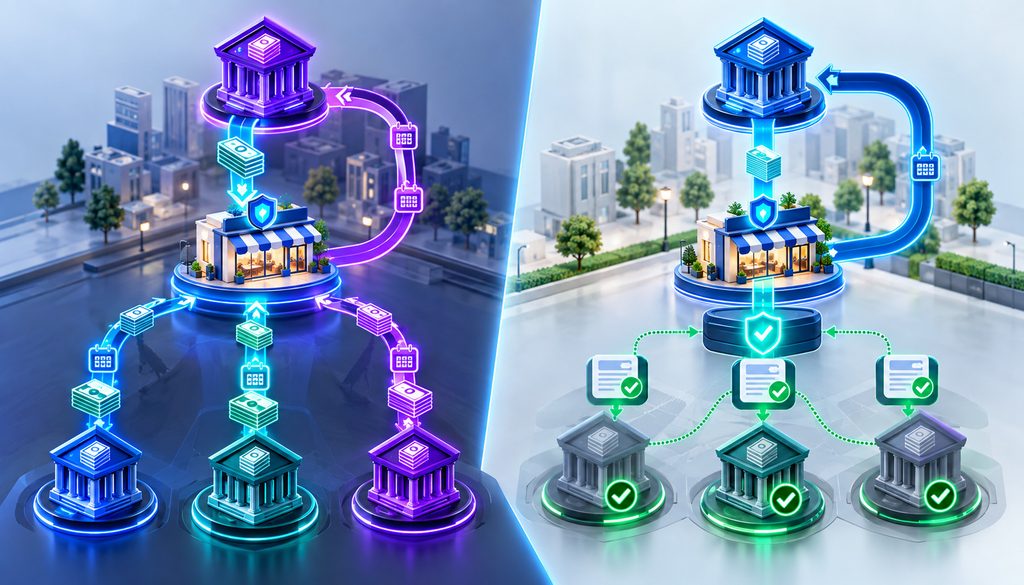
The key difference is structural: reverse consolidation generally supports payments while old positions remain; a true consolidation payoff uses replacement capital to retire specified old positions.
| Comparison | Reverse Consolidation | True Consolidation / Refinance |
| Existing positions | Remain until satisfied under their terms | Paid off at closing or settlement |
| Existing ACH withdrawals | Usually continue | Should cease once payoff is completed |
| New obligation | Layered alongside existing agreements | Replaces paid-off positions |
| Position count initially | Can increase | Usually decreases |
| Cash-flow relief | Created partly by scheduled new capital | Created by replacement repayment structure |
| Payoff letters | Important for comparison | Usually essential |
| Early-payoff terms | May remain unused | Can materially affect economics |
| UCC implications | Depend on new agreement and collateral | Depend on payoff/termination and replacement agreement |
| Main cost question | Old remaining payback + new RC payback | Replacement total cost after old positions are retired |
The correct reverse consolidation vs MCA consolidation loan comparison is therefore not:
Old weekly payments vs. new weekly payment.
It is:
Total dollars remaining under current positions + new financing cost + applicable fees + timing of every cash flow
A merchant should also confirm whether existing payoff quotes include contractual discounts or other prepayment adjustments.
When a True Payoff or Term Refinance Deserves Comparison
Before adding another position, it is worth evaluating when refinancing existing business funding may produce a more workable repayment structure. The comparison should account for current payoff amounts, replacement financing cost, payment frequency, repayment duration, and which existing withdrawals would actually disappear after closing.
A true MCA payoff deserves comparison when
The business qualifies for enough replacement capital to retire most or all existing positions.
This comparison becomes particularly important when existing agreements provide meaningful early-payoff reductions or when replacing multiple withdrawals substantially simplifies cash management.
The calculation still has to include the replacement financing’s entire contractual cost.
A term-loan refinance deserves comparison when
A bank, credit union, online lender, or other lender can provide sufficient proceeds under acceptable terms.
The financing structures themselves can also differ substantially, so merchants considering a replacement facility can compare SBA loans with alternative business funding before evaluating repayment duration, guarantees, collateral, qualification requirements, and total financing cost.
SBA’s current 7(a) program identifies refinancing current business debt as an eligible use of proceeds, subject to program requirements and lender underwriting.
Eligibility should never be assumed. Compare maturity, payment schedule, guarantees, collateral requirements, covenants, prepayment provisions, proceeds available for payoff, and total financing cost.
Direct funder negotiation deserves comparison when
The underlying business remains viable but current remittances have temporarily become unsustainable.
An existing provider may be willing to discuss a payment modification. Separately, the merchant should determine whether the actual contract contains an applicable reconciliation mechanism.
Reconciliation is especially important because courts examining MCA characterization have looked beyond whether reconciliation language merely appears on paper.
In the 2026 Richmond Capital decision, the New York Appellate Division noted that mandatory reconciliation provisions existed but reconciliation was not actually performed in practice, while payments operated as fixed amounts rather than good-faith estimates of receivables.
That is another reason not to assume that every agreement containing the word “reconciliation” functions identically.
When Reverse Consolidation May Only Postpone the Problem
A reverse consolidation merchant cash advance deserves additional scrutiny when:
- the business loses money before MCA payments;
- revenue continues to decline;
- new advances are primarily funding old financing payments;
- there is no credible path to reducing position count;
- management expects to stack again;
- scheduled RC funding ends before high-burden positions mature;
- existing agreements appear incompatible with another transaction;
- required net payments remain unaffordable;
- total dollar cost cannot be clearly calculated; or
- existing providers have already declared defaults.
Adding financing without a credible plan to reduce the position count can deepen the same liquidity problem the new funding was intended to address. Merchants evaluating another offer should therefore watch for broker red flags involving repeated MCA stacking, unclear costs, and inadequate review of existing obligations.
In these circumstances, additional financing may change the timing of the liquidity problem rather than resolve its cause.
25 Questions to Ask Before Signing Reverse Consolidation
Anyone evaluating MCA reverse consolidation explained by a broker should be able to obtain clear answers to these questions:
- Are any existing MCA positions actually being paid off?
- Which positions remain active after closing?
- What exact amount of new capital is contractually committed?
- Is the capital delivered upfront or in installments?
- What is the exact funding schedule?
- What is the purchased amount or total contractual repayment?
- What factor or other pricing mechanism applies?
- What fees are deducted before usable capital reaches the business?
- What is the effective usable cash after deductions?
- What must be paid to the new provider each week?
- Which existing payments continue unchanged?
- What is the projected net cash burden for every week?
- How long does the new agreement run?
- What happens if revenue declines?
- Is there a reconciliation provision, and exactly how does it operate?
- What happens if an existing provider declares default?
- Does any current agreement require consent for the new transaction?
- Have existing agreements been checked for additional-financing restrictions?
- Will a new UCC financing statement be filed?
- What total dollar amount will be paid across all existing and new positions if every agreement runs as modeled?
- What would a full consolidation payoff or refinance cost instead?
- Do existing positions offer contractual early-payoff reductions?
- Is broker compensation included in or deducted from the transaction?
- What happens if scheduled reverse-consolidation funding stops?
- What contractual events permit the provider to suspend future installments?
Question 20 should never be replaced by a statement such as “your weekly payment drops 40%.” Payment relief and total cost answer different questions.
Total-Cost Worksheet for Stacked Merchant Cash Advances
A merchant trying to consolidate stacked merchant cash advances should complete this worksheet using current agreements and payoff quotes.
| Position | Remaining Contractual Payback | Daily/Weekly Remittance | Estimated End Date | Current Payoff Quote | Contractual Early-Payoff Reduction |
| MCA 1 | $_____ | $_____ | _____ | $_____ | $_____ |
| MCA 2 | $_____ | $_____ | _____ | $_____ | $_____ |
| MCA 3 | $_____ | $_____ | _____ | $_____ | $_____ |
| New Reverse Consolidation | $_____ | $_____ | _____ | N/A | $_____ |
Total remaining contractual payments before RC = $_____
New RC contractual payback = $_____
Total layered contractual payments = $_____
Alternative full-payoff financing total repayment = $_____
Difference = $_____
A payoff letter matters because “balance” can mean different things in different documents. The remaining purchased amount, contractual payback, settlement figure, and discounted early-payoff quote may not be identical.
For merchantcapitalbrokers.com, the site’s informational guide on requesting an MCA payoff letter is the appropriate internal reference at this point once its live URL is confirmed. Linking the actual payoff guide is preferable to forcing a homepage or service-page link into this calculation.
Illustrative Example — Not an Industry Average
Consider a business generating $140,000 in average monthly gross revenue.
It currently has three stacked positions:
| Position | Weekly Remittance | Remaining Contractual Payback | Hypothetical Current Payoff Quote |
| MCA A | $3,500 | $45,000 | $41,000 |
| MCA B | $2,500 | $32,000 | $29,000 |
| MCA C | $2,000 | $28,000 | $25,000 |
| Total | $8,000 | $105,000 | $95,000 |
Using 52 weeks divided by 12 months, an $8,000 weekly burden is approximately:
$8,000 × 52 ÷ 12 = $34,667 per average month
The analytical payment load is therefore:
$34,667 ÷ $140,000 = approximately 24.8%
Again, 24.8% is not an underwriting threshold. It describes only this hypothetical merchant’s scheduled MCA payments relative to gross revenue.
Hypothetical reverse-consolidation proposal
Assume:
- committed funding: $50,000;
- funding schedule: $5,000 weekly for 10 weeks;
- illustrative factor: 1.40;
- contractual payback: $70,000;
- new weekly repayment: $2,000.
During supported weeks:
$8,000 existing payments + $2,000 RC payment − $5,000 RC funding = $5,000 immediate net cash burden
The merchant therefore supplies:
$8,000 − $5,000 = $3,000 less cash per supported week
That equals a 37.5% reduction in immediate out-of-pocket weekly burden:
$3,000 ÷ $8,000 = 37.5%
This is meaningful stacked MCA payment relief.
But the contractual dollars potentially remaining become:
$105,000 existing payback + $70,000 new RC payback = $175,000
The merchant also moves from three contractual positions to four until existing positions begin to finish.
Hypothetical true-payoff alternative
Now assume a separate qualifying refinance provides the $95,000 needed to satisfy the three current hypothetical payoff quotes.
Assume, solely for comparison, that the replacement financing carries a total contractual repayment of $121,600 and that no additional charges apply.
If the $95,000 actually retires all three positions, the post-closing contractual repayment is $121,600.
It is not:
$105,000 + $121,600
because the three old positions have been satisfied at their $95,000 payoff quotes rather than continuing alongside the replacement financing.
Position count also changes from three to one instead of temporarily increasing from three to four.
That arithmetic does not establish that the payoff alternative is “better.” Qualification, usable proceeds, timing, payment duration, operating margins, guarantees, collateral, payoff validity, contractual restrictions, liquidity requirements, and the replacement agreement all affect the decision.
It demonstrates why refinancing stacked MCAs and reverse consolidation must be compared on both cash-flow timing and full-life dollar cost.
Common Reverse-Consolidation Misconceptions
| Common Claim | What Is More Accurate |
| “Reverse consolidation pays off my MCAs.” | Existing positions commonly remain active. |
| “My payment drops, so my financing cost drops.” | Short-term cash burden and total contractual cost are separate measurements. |
| “It gives me one payment.” | Some structures leave several existing withdrawals plus a new obligation. |
| “Another position cannot affect my old agreements.” | Existing contracts may restrict additional financing, receivables sales, or security interests. |
| “If the weekly payment works, the deal works.” | Full-life cash flow and total dollars payable also matter. |
| “The factor spread is just interest.” | MCA pricing should not automatically be characterized as conventional-loan interest. |
| “A UCC filing tells me exactly what I owe.” | A financing statement does not establish the current contractual payoff amount. |
| “Every reverse consolidation is legally another MCA.” | Legal form depends on the new agreement and its operation. |
| “Every agreement called an MCA is legally a receivables purchase.” | Courts can examine substance and operation rather than accepting the label alone. |
Frequently Asked Questions
What is reverse consolidation for a merchant cash advance?
A reverse consolidation merchant cash advance generally supplies scheduled new capital to help a business carry payments on existing MCA positions. Those existing positions commonly remain active, while the merchant assumes a separate obligation to the new provider.
Does reverse consolidation pay off my existing MCAs?
Usually not in the structure commonly described as reverse consolidation. If new financing actually pays identified payoff quotes and closes the old positions, the transaction functions more like a true consolidation payoff or refinance.
How does the reverse consolidation weekly payment work?
The merchant may receive scheduled weekly support while existing MCA payments continue and a separate repayment is made to the new provider. The useful calculation is existing payments plus new repayment minus scheduled new funding.
Is reverse consolidation cheaper than paying off stacked MCAs?
Not necessarily. A reverse consolidation merchant cash advance can reduce immediate cash pressure while increasing total layered contractual payback. Compare current payoff quotes, remaining contractual payments, new payback, fees, and the complete payment timeline.
Does reverse consolidation add another MCA position?
It may add another receivables-purchase agreement, but not every reverse-consolidation product necessarily uses that legal structure. The new contract—not the marketing name—determines what obligation the merchant is actually entering.
Can reverse consolidation violate an anti-stacking clause?
Potentially. Existing contracts can restrict additional financing, additional receivables sales, competing security interests, or related conduct. Whether the new transaction breaches an agreement is contract-specific.
How many stacked MCAs can be reverse consolidated?
There is no universal statutory maximum or standardized approval number. Underwriting varies by provider and may consider position count, balances, remittance burden, deposits, revenue trends, payment history, defaults, and remaining duration.
Can I use a term loan instead of reverse consolidation?
Potentially. If the business qualifies and proceeds can be used to retire existing obligations, a term loan or other refinance can be compared with reverse consolidation. The comparison should include total repayment, maturity, collateral, guarantees, covenants, prepayment provisions, and cash-flow impact.
Should I ask existing funders to reduce payments before adding another position?
It is reasonable to determine what the existing contracts already permit and whether providers will discuss payment modification or applicable reconciliation before adding another obligation. Neither modification nor reconciliation should be assumed to be available.
Reverse Consolidation Merchant Cash Advance: Compare Timing and Total Dollars
A reverse consolidation merchant cash advance primarily addresses a timing and liquidity problem. It can reduce how much operating cash a merchant must supply during high-pressure weeks without automatically eliminating the underlying stacked merchant cash advances.
That means short-term relief and long-term cost can point in opposite directions.
A merchant can experience substantial stacked MCA payment relief today while simultaneously increasing the total contractual dollars that may leave the business over time. That is why the entire cash-flow curve matters more than an isolated weekly-payment comparison.
Before signing, identify which positions actually disappear, obtain current payoff quotes, calculate the remaining purchased amounts and contractual paybacks, identify all deductions and fees, map the funding and repayment schedule, and review existing agreements for additional-financing, receivables-sale, UCC, cross-default, and bank-account provisions.
Then compare the reverse consolidation merchant cash advance against a true payoff, MCA refinancing, term-loan refinance, direct funder negotiation, and any available payment modification using the same measurement:
How much usable capital reaches the business, how much cash leaves each week, how many positions remain, and how many total dollars must ultimately be paid?
That full-life calculation—not merely the promise of a smaller payment next week—is what shows whether reverse consolidation addresses the merchant’s underlying problem or mainly moves the liquidity pressure farther down the calendar.